The Proration Spread: How Taxes Paid in Arrears Drain Thousands from Seller Net Proceeds
The Core Takeaway
If you sell a home in a state that bills property taxes in arrears, you must credit the buyer at closing for the days you lived in the home during the unbilled tax period. Because the final county tax bill is unknown at settlement, standard real estate contracts use an estimated multiplier, typically 105% to 110% of the previous year's bill, to calculate this protective credit. For active sellers closing late in the calendar year, agreeing to this standard proration clause can automatically deduct thousands of dollars directly from your net proceeds. You can defend this equity by auditing exact municipal tax levies, negotiating the contract multiplier before signing, or executing a mutual reproration agreement to adjust the math once the actual bill arrives.
Municipal Accounting: The Mechanism of Arrears Taxation
In jurisdictions billing property taxes in arrears (such as Illinois, Ohio, Indiana, Texas, and Wisconsin), current calendar year collections fund prior year municipal obligations. Under an arrears schedule, tax bills issued and paid during the current calendar year satisfy municipal revenue requirements incurred during the previous calendar year.
During a property transfer, the conveyance deed guarantees the buyer clear, unencumbered title. Municipalities maintain statutory liens on real property for unpaid taxes, and these liens attach to the physical parcel regardless of ownership changes. Because the county assessor and collector deliver the actual tax bill to the current owner of record during the following calendar year, the buyer inherits the administrative obligation to pay the county.
To satisfy title underwriting standards, closing settlement agents enforce a contractual proration. The seller provides an immediate cash credit on the settlement statement to compensate the buyer for the specific number of calendar days the seller occupied the home during the unbilled period. The buyer receives this cash credit at settlement, holding the funds until the municipal tax collector issues the final billing invoice.
Contractual Proration Multipliers: The Financial Mechanics
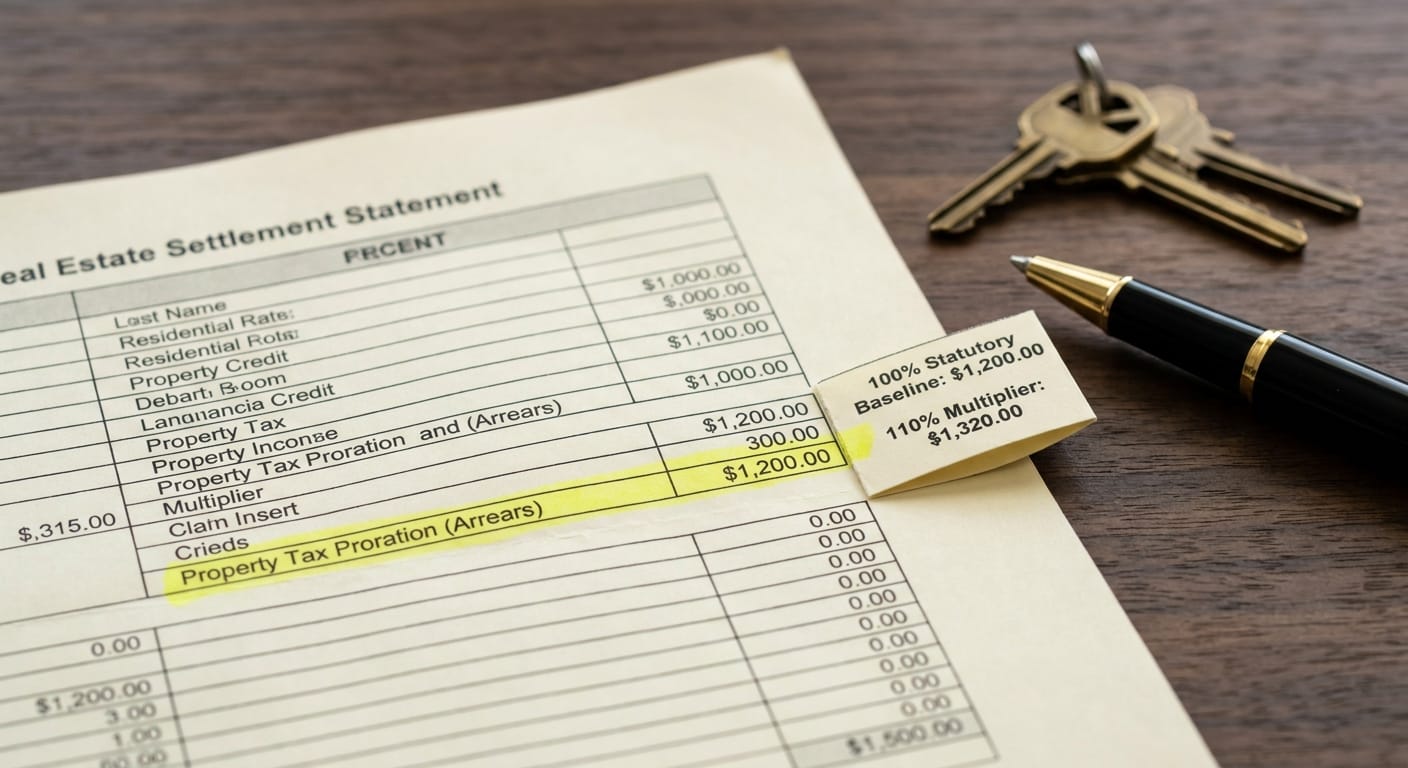
The baseline calculation for property tax prorations divides the most recent annual tax bill by 365 days to determine a per diem rate, which is then multiplied by the exact days of seller occupancy. However, municipal tax rates rarely remain static. Because school districts, park services, sanitary districts, and municipal governments periodically adjust their operational budgets, the actual tax bill for the current year almost always exceeds historical numbers.
To insulate buyers against pending tax increases, regional board contracts establish standard proration multipliers. In northern Illinois and parts of Ohio, standard board agreements default to 105% of the most recently ascertainable tax bill. In high growth regions or urban counties undergoing active quadrennial reassessments, such as Cook County, purchase contracts routinely demand a 110% proration multiplier.
The practical mechanics of a contractual multiplier function through a three step formula:
The historical annual tax base is multiplied by the contract factor (for example, 1.10) to generate a contractual Projected Tax Base.
The Projected Tax Base is divided by 365 days to establish a higher per diem tax rate.
The higher per diem rate is multiplied by the seller's days of ownership within the tax cycle to calculate the credit deducted from seller proceeds.
When applied across multiple quarters of accrued ownership, a 5% to 10% contractual surcharge extracts substantial capital from the transaction. What appears in contract negotiations as a minor procedural percentage represents an unverified cash transfer from the seller's proceeds to the buyer's closing balance.
Closing Date Timing and Accrual Exposure
The exact calendar date of closing determines the scale of a seller's proration liability. Transactions finalizing in January or February carry minimal exposure because accrued seller occupancy spans only a few weeks. Conversely, third and fourth quarter transactions force sellers to carry an extensive volume of unbilled daily liabilities.
Consider a suburban residence carrying an established historical annual property tax bill of $12,000. If the transaction closes on October 31st, the seller has accrued 304 days of residency within the current tax year.
The following compares seller proceeds under standard contractual proration baselines:
Annual Projected Tax Base: $12,000.00 (100% Statutory Baseline), $12,600.00 (105% Standard Board Multiplier), $13,200.00 (110% Elevated County Multiplier), resulting in a +$1,200.00 Net Variance.
Contractual Per Diem Rate: $32.88 (100%), $34.52 (105%), $36.16 (110%), resulting in a +$3.28 / day Net Variance.
Accrued Days of Seller Occupancy: 304 days across all baselines.
Buyer Settlement Credit Required: $9,995.52 (100%), $10,494.08 (105%), $10,992.64 (110%), resulting in a -$997.12 Net Variance.
Final Impact on Seller Net Cash: Baseline Deduction (100%), -$498.56 from proceeds (105%), -$997.12 from proceeds (110%), resulting in a -$997.12 cash reduction against the baseline.
At a standard 100% baseline calculation using the verified historical cost, the per diem rate is $32.88. Multiplied across 304 days, the seller's mathematical proration credit totals $9,995.52.
If the purchase contract stipulates a standard 110% multiplier, the projected tax base inflates to $13,200. This increases the contractual per diem rate to $36.16, elevating the required buyer credit to $10,992.64. The inclusion of the 110% multiplier extracts an additional $997.12 directly from the seller's net settlement proceeds.
The liability compounds in jurisdictions where taxes are collected in split semi-annual installments. In counties where first installment bills represent a fixed 55% of the previous year's total and second installments lag by several months, an unbilled second installment from the prior year combined with a late year current proration can easily force total settlement deductions beyond $16,000.
Reassessment Cycles and Underwriting Escrow Holdbacks
Proration expenses expand significantly when a transaction coincides with an active county reassessment cycle. Municipal assessing officials periodically recalculate market values across residential sectors to align tax assessments with recent sales data. If property valuations have risen across the taxing district, published assessment notices signal upcoming increases in composite tax bills.
When purchase agreements are drafted amid active reassessments, transaction attorneys and buyer representatives frequently strike out standard 105% provisions, replacing them with contractual demands for 115%, 120%, or 125% prorations. These higher percentage adjustments transfer thousands of dollars in contingent liabilities directly to the seller at the closing table.
In transactions where substantial assessment disputes or municipal backlogs prevent accurate rate projections, settlement agents or mortgage underwriters may require a formal escrow holdback. Under a typical holdback structure, the title company withholds $5,000 to $10,000 of seller net proceeds in a non-interest-bearing escrow account until the final county tax rate is certified. For sellers deploying their net proceeds directly into a concurrent property purchase, locked escrow funds create immediate liquidity friction and potential financing delays.
Defending Net Seller Proceeds: Four Pre-Contract Audit Steps
Sellers frequently treat standard board contract multipliers as non-negotiable closing fees. In practice, all proration provisions remain open to negotiation before contract execution. Sellers can defend their equity by auditing county data before agreeing to standard contract multipliers:
Audit Municipal Levy Increases: Examine the actual tax levy filings for local school boards, municipal districts, and county agencies. While property assessments determine how tax burdens are distributed, local levies dictate the total dollars collected. If taxing districts have frozen their levies or maintained balanced budgets, agreeing to a 110% proration multiplier credits the buyer for financial increases that do not exist.
Verify Statutory Assessment Caps: Multiple states maintain statutory caps that limit year over year increases in taxable assessed value. If state legislation restricts taxable value growth to 3% or 5% annually for existing properties, agreeing to an arbitrary 115% or 120% contract demand creates a needless financial concession.
Disclose and Adjust for Personal Exemptions: Sellers utilizing Senior Citizen, Veteran, or Long Time Homeowner exemptions pay discounted tax bills. If a purchase agreement calculates future prorations from an artificially low historical bill, the buyer will face an abrupt tax increase when exemptions reset post closing. Auditing and adjusting the baseline tax figure to reflect non-exempt status prevents post closing escrow disputes while establishing an equitable proration base.
Validate Physical Property Data: County assessor files occasionally list inaccurate square footage, unverified additions, or incorrect building classifications that artificially distort assessment ratios. Verifying property characteristics against county property record cards, permitted architectural archives, and verified building measurements ensures that underlying assessment data reflects physical reality.
Contractual Protection: The Mutual Reproration Addendum
When transaction parties hold diverging expectations regarding upcoming tax bills, executing a formal Reproration Agreement provides the most equitable contractual mechanism. Also designated as a Post Closing Tax Adjustment Agreement, this addendum binds both parties to a mathematical true-up once official county tax bills are published.
Under a standard mutual reproration framework:
Initial settlement calculations utilize a conservative baseline, typically 100% or 105% of the most recently published bill, allowing the seller to retain more net cash proceeds on closing day.
The addendum establishes a defined reproration window, requiring both parties to reconcile the proration within 30 days of the official final bill issuance.
If the certified bill exceeds the settlement credit, the seller tenders a payment for their proportional share of the exact variance.
If the certified bill is lower than projected, the buyer is contractually obligated to refund the excess credit directly to the seller.
Implementing a mutual reproration agreement replaces speculative contract multipliers with verifiable accounting, ensuring that closing deductions reflect actual municipal liabilities rather than unilateral risk buffering.
Strategic Settlement Scheduling and Net Equity Preservation
Beyond contractual clauses, transaction timing significantly affects proration balances. Sellers scheduling sales immediately following the satisfaction of a tax installment minimize their unbilled daily liability. Conversely, closing during the final weeks of a semi-annual billing cycle maximizes the cash reserve deducted at the settlement table.
When evaluating competing purchase offers, sellers must calculate net proceeds across every settlement line item rather than focusing exclusively on top line purchase prices. An offer proposing an immediate closing date with a 100% proration and a mutual reproration agreement often delivers superior net liquidity compared to a higher gross offer burdened with a 115% multiplier, late year closing, and escrow holdbacks. Incorporating arrears tax math into pre-listing financial models ensures sellers successfully defend their net transaction equity.
Defend Your Equity with a Net Yield Audit
Navigating arrears tax liabilities does not have to be a guessing game. The eppraisal Agent features a specialized net yield audit capability designed to help active sellers protect their net proceeds. Before listing, the platform factors localized municipal tax assessment cycles and contractual proration multipliers into comprehensive net proceeds models. By evaluating these closing adjustments alongside baseline estimated property valuations, the net yield audit empowers you to establish defensible pricing floors and accurately forecast your final settlement cash.
FAQs
A 110 percent tax proration clause reduces seller net proceeds by calculating your closing credit using an inflated future tax rate. Rather than crediting the buyer based on your last actual tax bill, the formula adds a 10% buffering penalty. On late-year sales, this inflated calculation can drain thousands of unexpected dollars directly from your final escrow payout.
Sellers pay a property tax credit at closing because many counties bill taxes in arrears, meaning the current year's taxes are not due until the following year. Since the buyer will inherit the physical property's future tax lien, the seller must reimburse them in cash for the exact number of days they occupied the home during the unbilled cycle..
Yes, standard property tax proration multipliers are completely negotiable before executing your real estate purchase contract. If municipal budgets show no major increases, sellers can negotiate for a baseline 100% calculation or deploy a post-closing mutual reproration agreement. This protects your equity by ensuring you only pay your mathematically verified liability.
Estimated property valuations are automated valuation models (AVMs) built from comparable sales, market trends, and property characteristics. Like any AVM, they carry a margin of variance and should be used as a directional data point alongside professional guidance..
The Factual Summary
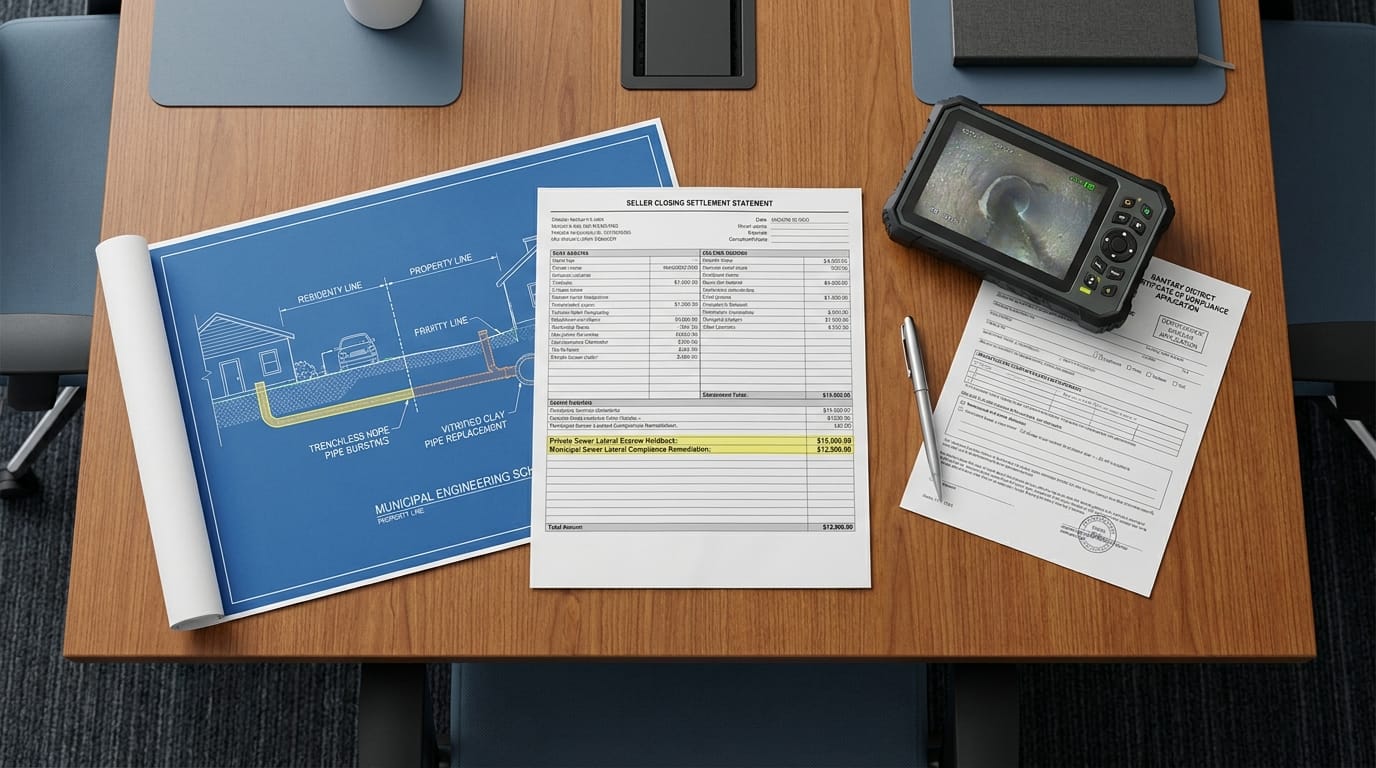
In an increasing number of cities operating under federal clean water agreements, local laws shift major underground infrastructure expenses onto home sellers. These point-of-sale ordinances require sellers to secure an official Private Sewer Lateral Certificate of Compliance before transferring property title. Because older clay, cast-
The Summary
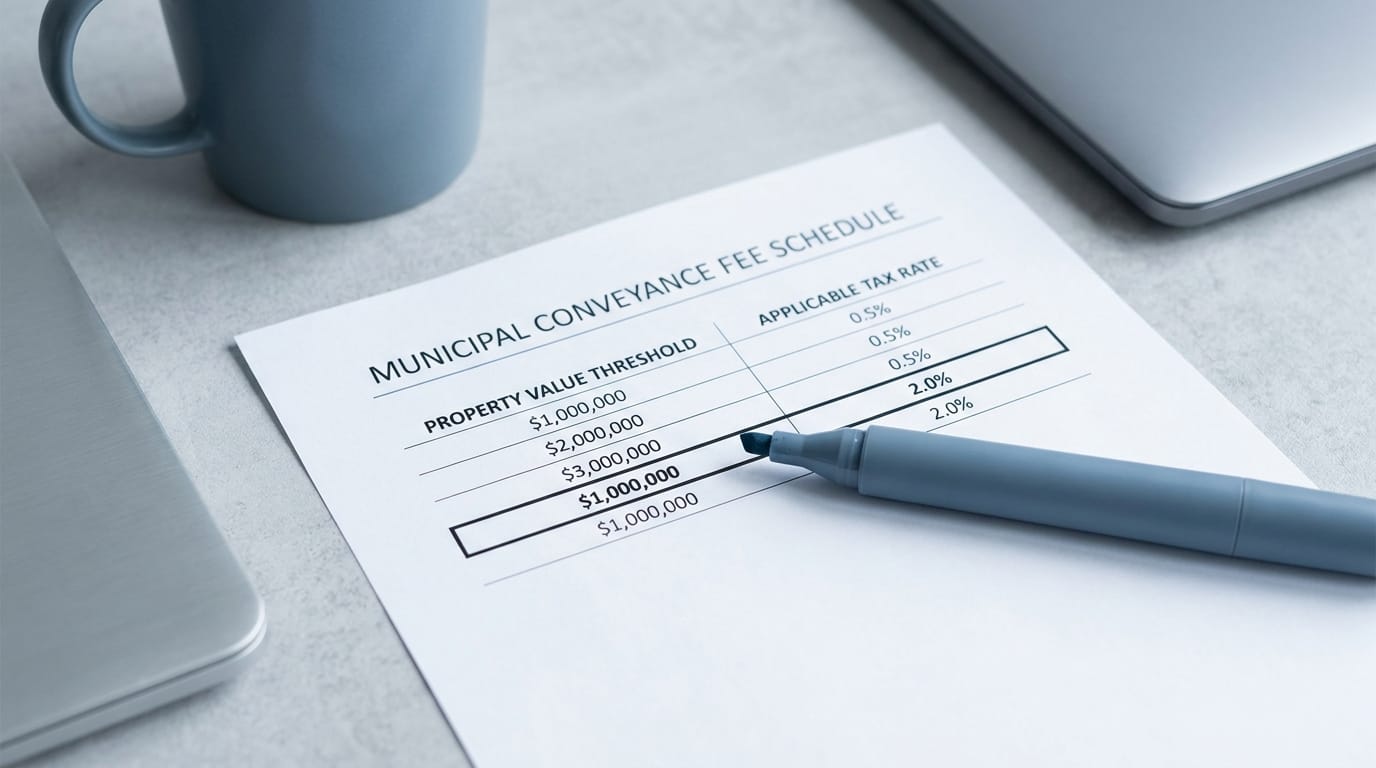
Progressive municipal real estate transfer tax brackets and localized tax cliffs can quickly reduce net seller proceeds. Crossing a statutory transaction threshold by a single dollar often triggers a higher tax rate against the entire gross purchase price.
When you prepare to put your home on the market,
The Summary
Following stricter federal lending guidelines and state-level structural inspection laws, condominium associations are now being forced to fully fund their reserves. This shifting regulatory landscape is triggering massive, unbudgeted special assessments for underfunded buildings. Active buyers must carefully audit an association's reserve study to calculate